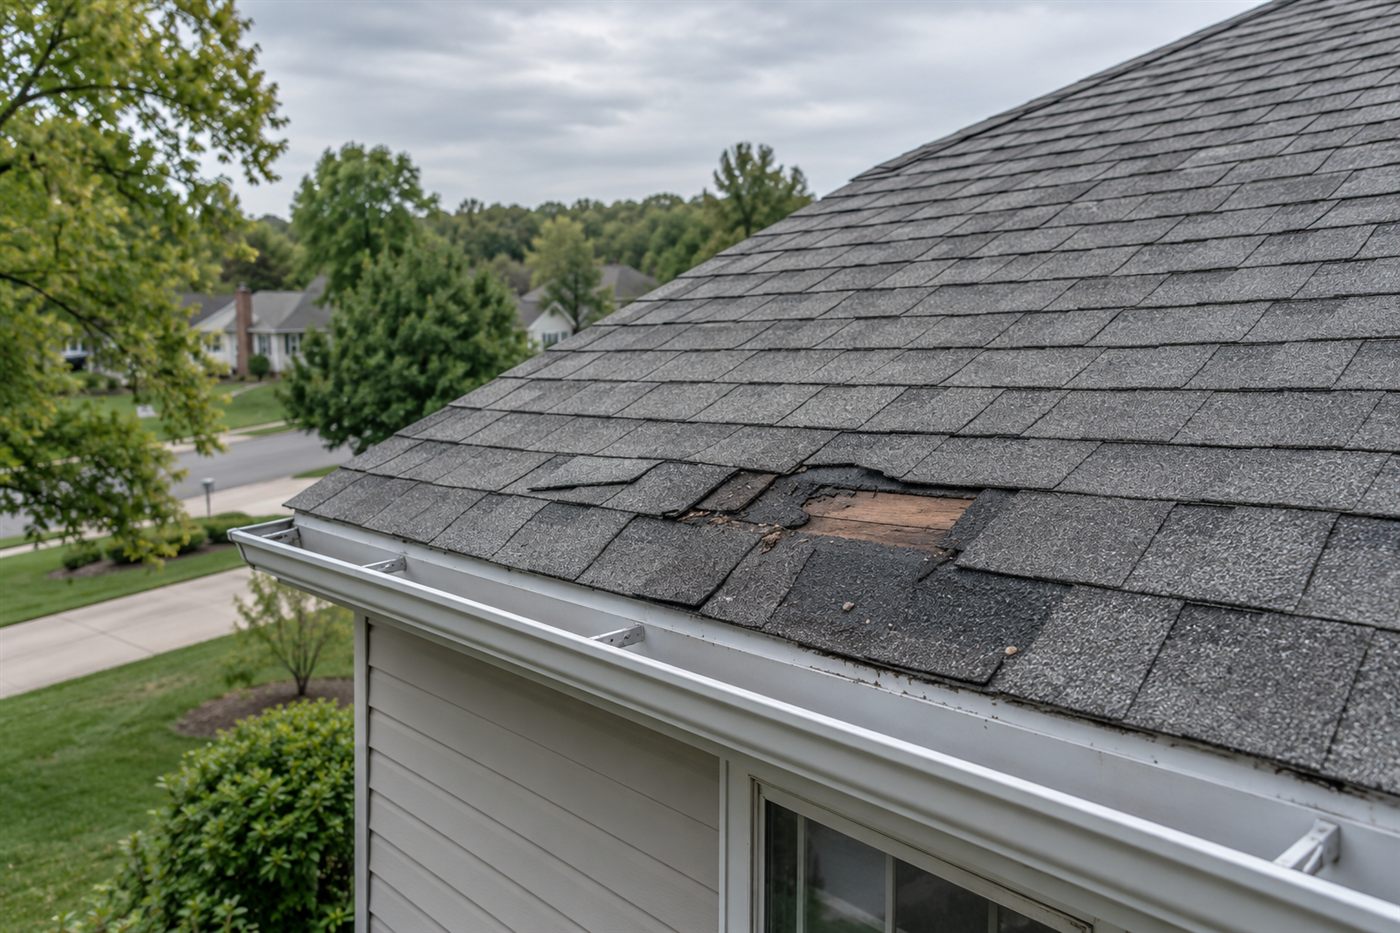
Whether a storm-damaged roof needs a partial repair or full replacement depends on the damage pattern, the roof’s repairability, available matching materials, current code requirements, and the homeowner’s policy. Your deductible and whether the roof is covered at actual cash value (ACV) or replacement cost value (RCV) determine how much of an approved claim may come out of your pocket. Strong documentation helps the insurer and roofing contractor compare the same facts.
Why Roof Repair and Replacement Opinions Differ
After wind or hail, an adjuster and a roofing contractor may reach different scopes because they answer different questions. The adjuster evaluates what damage is covered under the policy and what the insurer will pay. The contractor evaluates what work is needed to restore a serviceable roof.
A partial roof repair may make sense when damage is isolated, the surrounding roof remains sound, and compatible materials can be installed without harming adjacent areas. Full replacement may be the practical recommendation when damage is widespread, spot repairs cannot be completed reliably, matching materials are unavailable, or required work affects a larger roofing system.
Matching is often part of the discussion, but it does not automatically guarantee a new roof. Under Ohio’s claims-settlement rule, when a qualifying replacement-cost loss requires an exterior item to be replaced and the replacement does not match in quality, color, or size, the insurer must replace enough to create a reasonably comparable appearance. How that rule and your policy apply to a particular roof is a coverage question for the insurer or a qualified insurance professional.
Start With Your Deductible
A deductible is the portion of a covered loss you pay. If your deductible used to be $1,000 and is now $5,000, that change can substantially alter the economics of a claim. A technically repairable roof does not become unrepairable because of a high deductible, but the expected covered repair cost may not exceed what you must pay yourself.
Check the declarations page and endorsements before filing. Look for:
- Your standard property deductible
- Any separate wind or hail deductible
- Roof-specific payment terms
- ACV, RCV, or roof-surface limitations
- Deadlines for reporting damage and completing repairs
The National Association of Insurance Commissioners recommends checking the deductible first; for minor damage, paying for repairs directly may make more sense, although hidden damage is a reason to obtain a professional inspection before deciding.
ACV vs. RCV: What Changes in a Roof Claim?
Actual cash value (ACV) generally means replacement cost minus depreciation. Depreciation may reflect age, pre-loss condition, expected useful life, and replacement cost. Replacement cost value (RCV) generally covers the cost of repairing or replacing covered damage with property of similar kind and quality, without deducting depreciation, subject to the deductible, policy limits, and other terms. The NAIC’s roof-claim explanation illustrates how two identical roof losses can produce very different payments under ACV and RCV coverage.
Do not assume the entire homeowners policy treats the roof the same way as the rest of the house. A policy may provide RCV for much of the dwelling but ACV for roof surfaces. With some RCV claims, the insurer first pays ACV and releases the difference—called recoverable depreciation—after receiving proof that covered work was completed. Deadlines may apply, so ask the adjuster what documentation is required and when it is due.
How to Document Roof Damage Without Missing Key Proof
1. Record the Conditions Promptly
Note the date and approximate time of the storm and what you observed, such as hail, high wind, fallen branches, active leaking, or missing shingles. Save relevant weather alerts if available.
2. Photograph Damage Safely
From the ground or another safe location, take wide views of each roof slope and closer images of visible damage. Photograph displaced shingles, debris, gutters, downspouts, siding, windows, attic moisture, ceiling stains, and damaged belongings. Include unaffected areas for context. Do not climb onto a wet, steep, or unstable roof.
3. Prevent Additional Damage
After documenting the original condition, take reasonable temporary steps to limit further water intrusion. Keep receipts for tarps, emergency service, and materials. The NAIC advises homeowners to make essential temporary repairs but speak with the insurer before permanent work that has not been authorized.
4. Get a Detailed Roofing Inspection
Ask for labeled photographs and a written, itemized estimate. It should identify damaged components, quantities, materials, labor, and the reason each repair or replacement step is needed. Written contractor bids with line-by-line materials and pricing can make claim review faster and clearer.
5. Keep One Complete Claim File
Save the policy, declarations, endorsements, claim number, insurer estimate, contractor estimate, photos, receipts, emails, and notes from every call. Record names, dates, and next steps. Keep copies of everything submitted.
What to Do When the Scopes Do Not Match
Compare the insurer’s estimate and the contractor’s estimate line by line. Ask the adjuster to explain omitted items, depreciation, deductibles, and policy limitations in writing. In Ohio, an insured may request documentation detailing ACV depreciation deductions.
Ask the roofer to support any disputed construction item with measurements, photographs, material information, and a clear explanation of why a localized repair is or is not technically workable. If new damage is uncovered or the estimates rely on different facts, notify the insurer and ask about reinspection or supplemental review before proceeding.
A roofer can document roof conditions and construction costs, but the insurer determines coverage. For policy interpretation or a claim dispute, speak with your agent, insurer, the Ohio Department of Insurance, a licensed public adjuster, or an attorney as appropriate.
Get a Clear Roof Assessment Before You Decide
If your Dayton or Miami Valley home has storm damage, we can inspect the roof, document what we find, and explain the practical repair and replacement options. Contact Enterprise Roofing or call us at 937-298-8664 to request a free inspection or quote before small problems become larger ones.
Nov. 03, 2026
Buying a Home in Dayton? The Roof Questions Smart Buyers Ask First
Oct. 19, 2026
How Fuel Prices Can Affect Roof Pricing
Oct. 05, 2026
Roof Repair or Replacement After Storm Damage? A Dayton Homeowner’s Insurance Guide
Sep. 22, 2026
Choosing the Right Roofing Material for Your Home
Sep. 08, 2026